

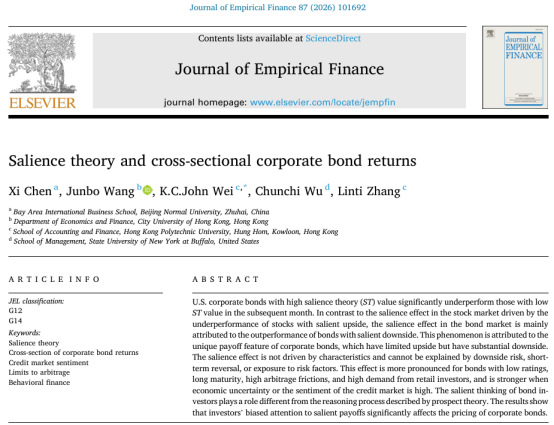
Xi Chen, Junbo Wang, K.C.John Wei, Chunchi Wu, Linti Zhang
Journal of Empirical Finance
https://www.sciencedirect.com/science/article/abs/pii/S0927539826000071?via%3Dihub
JEL CLASSIFICATION International Journal of Information Management
G12; G14
ABSTRACT
U.S. corporate bonds with high salience theory (ST) value significantly underperform those with low ST value in the subsequent month. In contrast to the salience effect in the stock market driven by the underperformance of stocks with salient upside, the salience effect in the bond market is mainly attributed to the outperformance of bonds with salient downside. This phenomenon is attributed to the unique payoff feature of corporate bonds, which have limited upside but have substantial downside. The salience effect is not driven by characteristics and cannot be explained by downside risk, short-term reversal, or exposure to risk factors. This effect is more pronounced for bonds with low ratings, long maturity, high arbitrage frictions, and high demand from retail investors, and is stronger when economic uncertainty or the sentiment of the credit market is high. The salient thinking of bond investors plays a role different from the reasoning process described by prospect theory. The results show that investors’ biased attention to salient payoffs significantly affects the pricing of corporate bonds.
KEYWORDS
Salience theory; Cross-section of corporate bond returns; Credit market sentiment; Limits to arbitrage; Behavioral finance
